France’s debt crisis deepens, colliding with bond-market pressure
Public debt has reached 115.6% of GDP, borrowing costs are approaching two-decade highs and political divisions are complicating efforts to reduce the deficit without triggering further social unrest.
France is facing an increasingly difficult economic balancing act: investors are demanding a credible plan to control government borrowing, while students, workers and political parties are resisting spending cuts that could affect public services and social benefits. The standoff is raising concerns about the country’s fiscal outlook and the potential consequences for the wider eurozone.
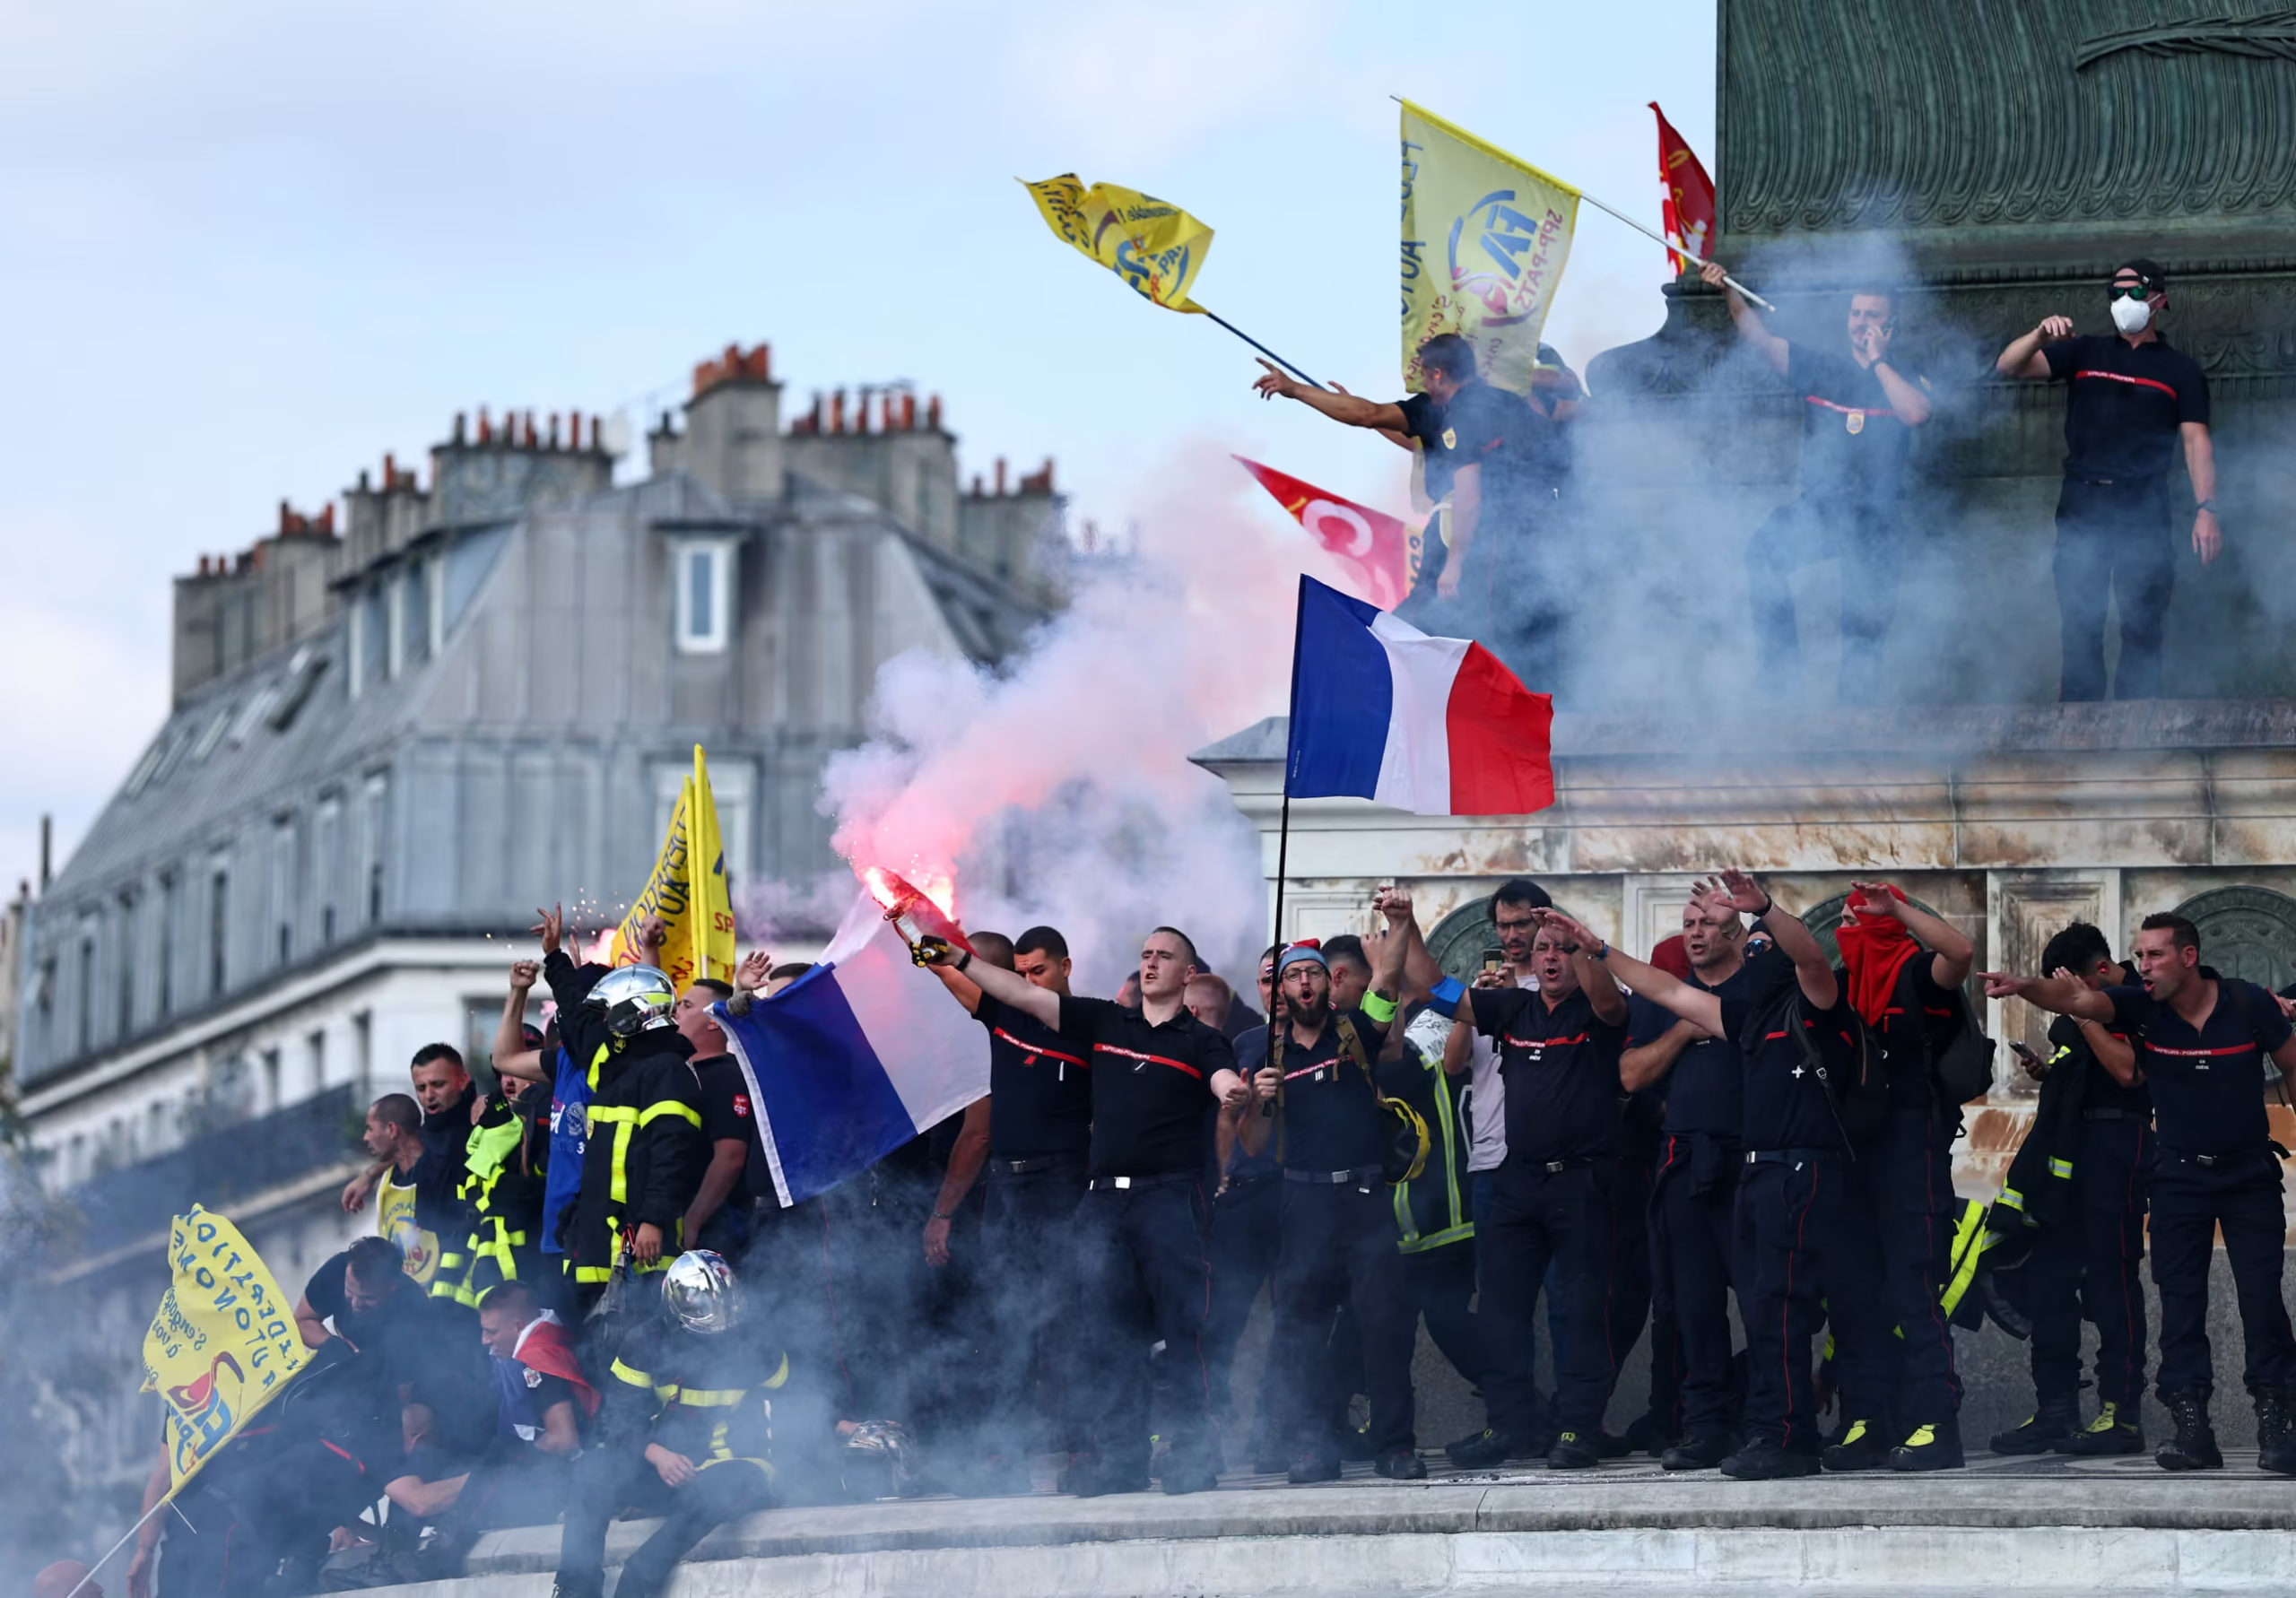
The Guardian reported on 10 October that rising market anxiety is coinciding with renewed protests and political uncertainty ahead of the 2027 presidential election. The pressure comes as President Emmanuel Macron’s government struggles to secure parliamentary support for a sustainable budget strategy.
Official figures from France’s national statistics institute, INSEE, show that public debt reached €3.46 trillion at the end of 2025, equivalent to 115.6% of gross domestic product (GDP). The public budget deficit stood at 5.1% of GDP that year, following 5.8% in 2024. The debt ratio has continued to rise, limiting the government’s room to respond to economic shocks without increasing borrowing further.
The outlook for the deficit remains challenging. The government now expects it to reach 5.4% of GDP in 2026, above the European Union’s 3% reference threshold. Its proposed target for 2027 is 5%, an improvement that would still leave France substantially above the bloc’s benchmark. Reuters reported on 8 October that eurozone finance ministers and European Central Bank officials were pressing Paris to adopt a credible 2027 budget to restore market confidence.
Bond markets raise the cost of inaction
Investors have become increasingly sensitive to France’s fiscal position and the uncertainty surrounding its next budget. In early October, yields on 10-year French government bonds approached 5%, their highest levels since 2002, according to reporting by Le Monde and The Guardian.
Bond yields rise when investors demand greater returns to hold government debt, often reflecting concerns about fiscal risks, inflation or political uncertainty. Higher yields can increase the cost of refinancing maturing debt and servicing new borrowing, gradually placing additional pressure on public finances.
France is not facing these pressures in isolation. Bond markets in the United States and United Kingdom have also experienced volatility amid concerns over public borrowing and interest rates. However, France faces an additional challenge: political fragmentation has made it difficult to secure agreement on a budget capable of delivering sustained deficit reduction.
Reuters reported that France plans to borrow around €340 billion in 2027, underlining the importance of maintaining investor demand for government bonds. A prolonged loss of confidence could make that financing more expensive, although elevated yields do not, by themselves, mean that a sovereign default is imminent.
Businesses hold back as policy uncertainty grows
The fiscal dispute is beginning to affect business confidence. A survey by Medef, France’s largest employers’ federation, cited by The Guardian, found that 82% of participating firms were pessimistic about the impact of the next government’s economic policy. Another 66% said their businesses could become vulnerable or face bankruptcy if policy deadlock continued for five years.
These figures reflect reported business sentiment rather than an economy-wide forecast of insolvencies. Nevertheless, they highlight a potential feedback loop: uncertainty can delay investment, weaker investment can constrain growth and slower growth can make debt reduction more difficult.
France retains important economic strengths, including established infrastructure, a diversified industrial base and relatively low electricity costs in parts of its economy. The immediate challenge is therefore not simply the size of its debt, but whether political institutions can produce a credible fiscal plan without undermining growth or public confidence.
Pension reform and the politics of austerity
Macron’s attempt to raise the statutory retirement age from 62 to 64 has become a defining example of the political difficulty of fiscal reform. The measure was intended to improve the finances of France’s pension system, but parliamentary deadlock and political opposition left implementation stalled at 62 years and nine months.
The dispute illustrates the tension between long-term fiscal sustainability and the immediate social costs of reform. Measures that reduce public expenditure can improve the budget balance, but they may also provoke protests, weaken household demand or intensify opposition to the government.
Political uncertainty is expected to remain a central concern as France approaches its 2027 presidential election. Marine Le Pen, associated with the far-right National Rally, has advocated reversing the pension-age increase while also proposing a mechanism to constrain borrowing. Jean-Luc Mélenchon, leader of the left-wing France Unbowed movement, represents a different political approach to public spending and economic policy.
Economists interviewed by The Guardian have warned that a contest between candidates advocating sharply different economic programmes could increase investor uncertainty. One analyst raised the possibility of renewed debate over France’s relationship with the euro, but this remains a scenario rather than an established policy outcome or a forecast that France will leave the currency union.
Can Europe provide a safety net?
The European Central Bank could potentially play a role in containing severe financial-market disruption, but support would not necessarily be unconditional. Eurozone financial assistance and relevant ECB mechanisms operate under specific eligibility requirements and policy conditions.
France’s size makes the issue particularly consequential. As the eurozone’s second-largest economy, a major French financing crisis would have implications for European banks, sovereign bond markets and the wider currency union. A rescue could also be considerably more complex and expensive than assistance for a smaller economy.
French central bank officials have denied that emergency support is currently required, while European policymakers have urged the government to establish a credible budget framework. The immediate objective is to prevent uncertainty from escalating into a more serious financing problem.
The country’s options involve difficult trade-offs. Faster deficit reduction could reassure investors but risk intensifying opposition to spending restraint. Delaying adjustment could protect some public expenditure in the short term while leaving the government exposed to higher financing costs. Measures that support productivity and economic growth could improve the debt outlook over time, but their effects would not necessarily be immediate.
France’s fiscal challenge is therefore as much political as economic. The government must demonstrate that it can manage public borrowing while maintaining essential services and sustaining growth. Whether it can reach that balance will influence not only French public finances but also confidence in the resilience of the eurozone.
