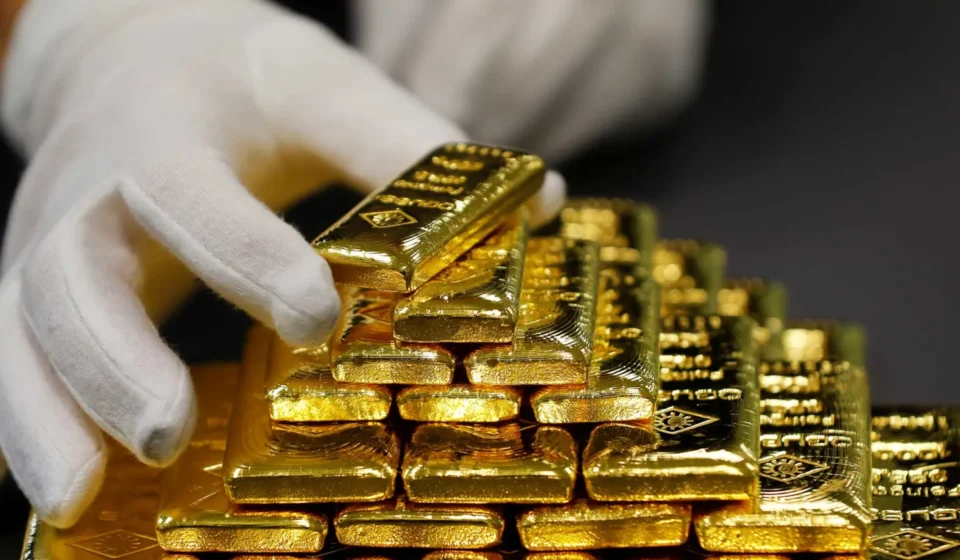
Gold prices have fallen sharply from their record high in January, with the precious metal dropping below $3,700 an ounce this week as rising US Treasury yields, a stronger dollar and expectations of higher interest rates reduce its appeal to investors.
The decline marks a significant reversal after an extraordinary rally in which gold recorded 53 all-time highs during 2025. Prices reached a historic peak of $5,589.38 an ounce on 28 January 2026 before losing momentum. By Thursday, 19 November, gold had fallen to a 14-month low, extending a correction that has erased roughly one-third of its value from the January peak.
According to Reuters, spot gold fell to $3,674.13 an ounce on Thursday, after touching an intraday low of $3,667.19. US gold futures also declined, reflecting growing expectations that the Federal Reserve could maintain or increase borrowing costs.
Higher interest rates increase the cost of holding gold
A major factor behind the downturn is the changing relationship between gold, interest rates and the US dollar.
Unlike government bonds or interest-bearing savings products, gold does not generate regular income. When Treasury yields rise, investors can earn higher returns from other assets, increasing the opportunity cost of holding the precious metal.
A stronger US dollar also puts pressure on gold because the metal becomes more expensive for buyers using other currencies.
Suki Cooper, global head of commodities research at Standard Chartered, told CNBC that gold can behave either as a commodity or as a currency, depending on the forces shaping the market. She said the earlier rally was supported by strong physical demand and renewed interest from long-term investors, particularly through gold-backed exchange-traded funds (ETFs).
However, the market environment has changed. Higher yields and a stronger dollar have shifted investor calculations, while uncertainty over future Federal Reserve policy has encouraged some investors to reduce their exposure.
Evan Mills, a financial adviser at Scholar Financial Advising, said expectations of higher interest rates had weakened gold’s appeal. He noted that money market funds offering returns of around 4% to 5% had become more attractive compared with an asset that produces no regular income.
From record ETF demand to a market correction
Gold’s rise was supported by a substantial increase in investment demand. According to the World Gold Council, global gold-backed ETFs attracted a record $89 billion in inflows during 2025. Their combined assets under management more than doubled to $559 billion, while holdings reached approximately 4,025 tonnes.
The weaker dollar, lower bond yields and concerns about global debt also helped strengthen demand earlier in 2026.
The market’s direction changed after January. The rapid rise in prices encouraged profit-taking, while changing expectations about US monetary policy made alternative investments more attractive.
Cooper also said the conflict in the Middle East altered how some investors used gold. Rather than holding it purely as a safe-haven asset, investors began selling the highly liquid metal to raise cash during periods of market pressure.
The result has been a sharp correction despite gold’s continuing role in long-term investment strategies.
Analysts remain divided over the outlook
Market experts disagree over how far prices could fall and when a recovery might begin.
Marc Chandler, managing partner and chief market strategist at Bannockburn Capital Markets, said gold could move towards $3,500 to $3,600 an ounce. He warned that there was no clear technical indication that the market had reached its lowest point and advised investors against rushing to buy during the decline.
Chandler also argued that gold remained expensive compared with its longer-term historical averages.
Other analysts remain more optimistic about the metal’s longer-term prospects. Amy Gower, head of metals and mining strategy at Morgan Stanley, told CNBC that there were still substantial reasons for investors to maintain exposure to gold despite the correction.
Philip Diehl, a former director of the US Mint and president of US Money Reserve, also maintained that the fundamental reasons behind the previous bull market remained relevant. He argued that geopolitical uncertainty and changes in international economic relationships continued to support gold’s longer-term investment case.
Diehl expects prices to recover in 2027 if oil markets stabilise and inflationary pressures ease, allowing interest rates to settle.
Central banks continue to provide support
Despite the decline in market prices, central banks remain an important source of demand.
The World Gold Council reported that central banks purchased a net 61 tonnes of gold in September 2026, the highest monthly total of the year so far. Reported net purchases for the first nine months reached 228 tonnes, although this was 7% lower than during the same period in 2025.
Poland and China were among the leading buyers, while several other countries also continued to increase their gold reserves.
This continued institutional demand suggests that the longer-term role of gold in reserve diversification has not disappeared, even as private investors reassess its short-term attractiveness.
Gold as insurance rather than a growth investment
For individual investors, the recent decline has renewed debate about the purpose of holding gold in a portfolio.
Mills argued that gold should not necessarily be viewed as a short-term growth investment. Instead, he described it as a form of financial insurance that can help diversify a portfolio during periods of currency weakness, geopolitical uncertainty or market instability.
The distinction is important: an asset can retain its long-term diversification value while still experiencing substantial price declines, particularly when investors have paid unusually high prices to acquire it.
The immediate outlook for gold will depend heavily on the direction of US interest rates, Treasury yields and the dollar. Continued monetary tightening could create further pressure, while renewed geopolitical uncertainty or a shift towards lower interest rates could restore some demand.
For now, the market is facing a difficult adjustment after an exceptional rally. The longer-term case for gold remains a subject of debate, but its recent performance has demonstrated how quickly investor preferences can change when the financial conditions supporting a rally begin to reverse.
Sources: Kevin Williams, CNBC, Gold’s bad year is getting worse. Why its price keeps falling; Reuters, Gold hits 14-month low as strong dollar, rate bets weigh; World Gold Council, December caps off a record year; World Gold Council, Central bank gold statistics – September 2026.