IMF warns US growth strategy cannot resolve rising debt burden
The International Monetary Fund has warned that stronger economic growth alone will not be enough to rein in the United States’ widening budget deficit and rising public debt, putting renewed focus on the need for spending restraint and credible fiscal reforms.
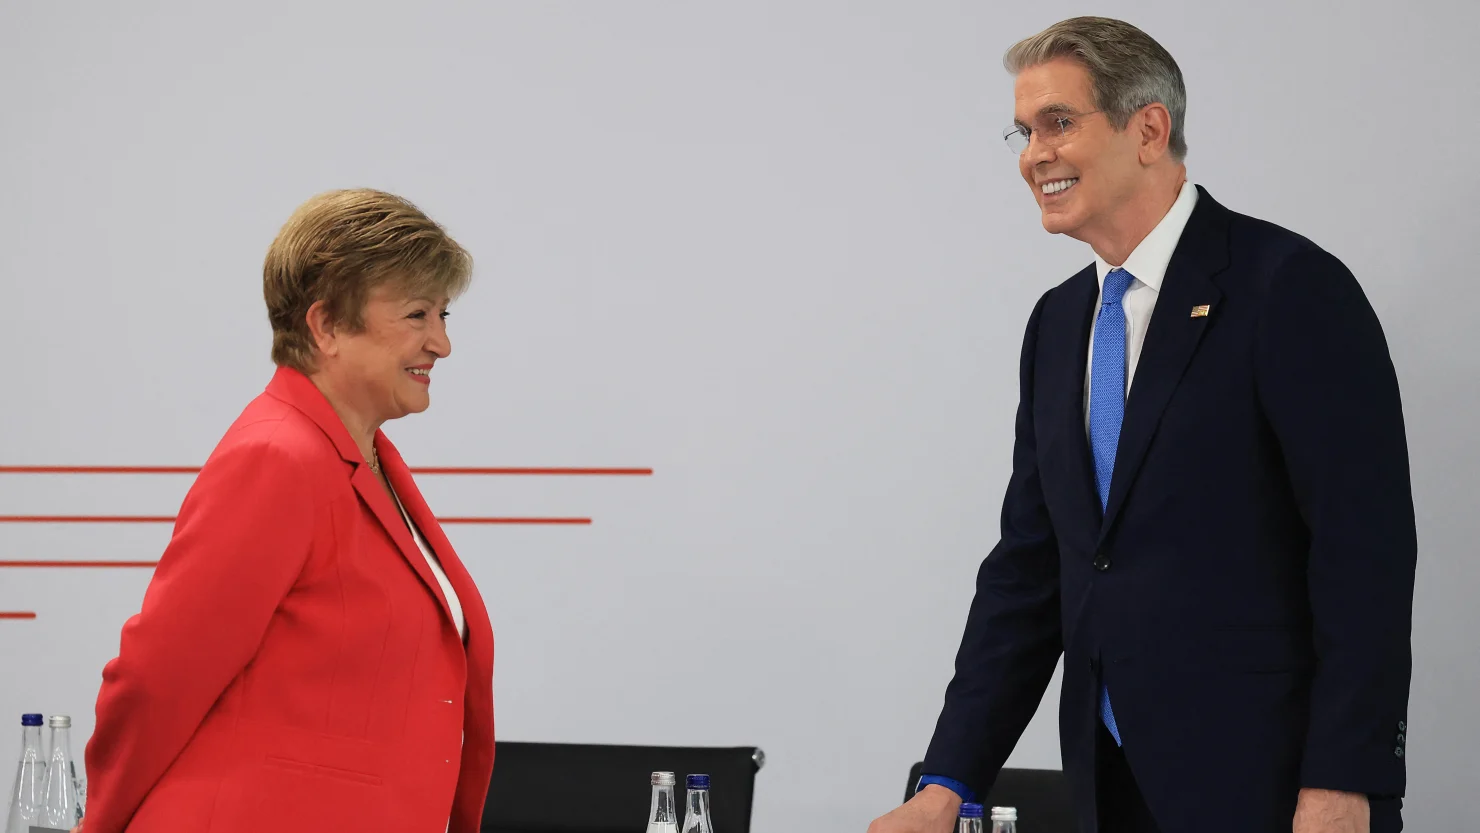
IMF Managing Director Kristalina Georgieva said on 14 October that growth could support the government’s finances but would not deliver the necessary adjustments quickly enough. Her comments challenge US Treasury Secretary Scott Bessent’s argument that sustained annual growth above 3%, combined with spending restraint, could lower the debt-to-GDP ratio.
The concern is significant because US federal debt has exceeded the size of the country’s annual economic output. According to the CNBC report, the national debt has surpassed $40 trillion, while the federal budget deficit is expected to exceed 6% of GDP in the fiscal year that ended on 30 September 2026.
The disagreement centres on whether economic expansion can reduce the debt burden quickly enough without more direct action on taxation and government spending. The Trump administration has pointed to investment in artificial intelligence, the reshoring of manufacturing and tax measures as drivers of stronger growth. Bessent has argued that growth above 3% could help reverse the upward trajectory of debt relative to GDP.
However, the IMF’s latest projections suggest a substantial gap between that ambition and the current outlook. The fund forecasts US economic growth of 2.3% in both 2026 and 2027, below Bessent’s stated target. It also projects gross government debt reaching around 142% of GDP by 2031. The IMF had already called for a credible fiscal consolidation plan in its 2026 assessment of the US economy.
The fiscal challenge is unfolding as US Treasury yields remain elevated. CNBC reported that the benchmark 10-year yield was around 5.2% on 14 October, near its highest level since 2002. Higher yields can increase the government’s borrowing costs as debt is refinanced, leaving less budgetary room for other priorities.
The implications extend beyond Washington. US Treasury securities influence borrowing costs across international financial markets, meaning persistent fiscal concerns in the world’s largest economy can contribute to tighter financing conditions elsewhere. The IMF has warned that elevated debt and benchmark yields can also intensify pressure on lower-income economies already struggling with debt-servicing costs.
Reducing the deficit would require decisions on spending, revenue or both—choices that can carry economic and political costs. Abrupt cuts may weaken demand or affect public services, while additional borrowing could prolong fiscal vulnerabilities. Stronger growth can improve tax receipts, but its effect depends on how quickly growth materialises and whether spending and revenue trends remain sustainable.
Georgieva’s warning is therefore not that growth is irrelevant, but that it cannot substitute for a credible medium-term fiscal strategy. For investors, the key question is whether the US can stabilise its debt trajectory without undermining economic expansion or further unsettling bond markets.
Sources
